Bring your retirement timeline, income targets, and liquidity questions. You do not need to choose a product before booking, and a consultation does not obligate you to purchase a contract.
Sarah Owens
Independent Insurance Specialist • NPN #22361652
NIPR Verified • 16+ Top-Rated Carriers
"Personalized solutions, trusted carriers, and peace of mind for your future—built by comparing 16+ top-rated insurers side-by-side."
When is an annuity appropriate for your retirement?
Annuities solve specific structural challenges that direct market investments cannot address alone:
Approaching Retirement Within 1–5 Years
Transitioning from aggressive asset accumulation to capital preservation, insulating near-term retirement funds from sequence-of-returns market crashes.
Rolling Over a Previous Employer 401(k)
Consolidating legacy employer 401(k) balances into a self-directed, protected IRA annuity without incurring tax penalties or distribution withholdings.
Creating a Personal Pension Stream
Establishing a contractually guaranteed lifetime income payment that deposits predictably each month to supplement Social Security and cover essential living costs.
Desiring Complete Principal Protection
Locking accumulated retirement gains into contracts with a 0% floor so negative market years never reduce principal balance.
Locking in Multi-Year CD Alternatives (MYGA)
Securing competitive fixed interest rates for 3, 5, or 7 years with tax-deferred compounding, outperforming standard taxable bank certificates of deposit.
Outliving Savings Anxiety (Longevity Risk)
Transferring the financial risk of living to age 90, 95, or 100 to the insurance carrier through contractually guaranteed lifetime withdrawal riders.
A major market drop in your final working years can delay retirement by 5+ years.
Experiencing a 25% portfolio correction right as you begin distributions is called sequence-of-returns risk. Establishing a protected annuity income floor shields you from having to sell equities at a loss. Call Sarah today to evaluate your retirement income safety net.
What Fixed & Indexed Annuities deliver.
Backed by the financial reserves of licensed Nationwide life insurers, annuities provide specific contractual safety features:
Guarantees that your deposited principal and previously credited interest cannot be reduced by stock market downturns or crashes.
Generates a predictable, contractual income payment that cannot be outlived, continuing uninterrupted for the rest of your life.
Interest earnings compound without annual 1099 tax erosion until distributions begin, allowing capital to grow faster over time.
Upon death, remaining contract account values transfer directly to your named beneficiaries without Nationwide probate court delays or public filing.
Commitments, liquidity, & rules.
Annuities are long-term insurance contracts with defined contractual restrictions:
Withdrawing more than the annual penalty-free allowance (typically 10%) during the contract surrender period triggers significant percentage penalties and MVAs.
Annuities are insurance contracts backed solely by the financial strength of the issuing life company, not the FDIC or any government agency.
Because annuities receive statutory tax deferral, the IRS imposes a 10% penalty on earnings withdrawn before age 59½, in addition to ordinary income tax.
In exchange for the 0% downside guarantee, FIAs cap your index gains. If the S&P 500 rises 30%, your credited interest is capped at your contract limit (e.g. 9%).
Comparing the 4 major annuity categories.
Selecting the right annuity structure depends on whether your priority is fixed yield, market-linked accumulation, or immediate lifetime income:
Contracts that lock in a guaranteed fixed interest rate for a chosen term (commonly 3, 5, or 7 years). Delivers complete predictability and principal preservation without stock market exposure.
Credits interest based on the positive performance of an external market index (such as the S&P 500) subject to caps or participation rates, with a contractually guaranteed 0% floor against market losses.
Optional contract riders that generate a predictable, guaranteed income stream for life—even if your contract account value is eventually reduced to zero through longevity.
Converts a single lump-sum savings deposit into an immediate stream of monthly retirement income payments commencing within 30 to 365 days.
Annuitization vs. Guaranteed Lifetime Withdrawal Benefit (GLWB) Riders
Traditional annuitization permanently surrenders control of your lump-sum principal to the insurance company in exchange for an irrevocable monthly check. In contrast, modern Guaranteed Lifetime Withdrawal Benefit (GLWB) riders allow you to generate guaranteed lifetime income payments while retaining full ownership of your underlying account value, leaving any remaining principal to your heirs upon passing.
How the 5-Step Annuity & Retirement Review works
A structured, fiduciary-minded roadmap designed to protect retirement principal, model guaranteed cash flow, and ensure comfortable liquidity.
Discover
Audit guaranteed retirement income against fixed living expenses, identify monthly deficits, and protect emergency liquidity reserves.
Compare
Sarah compares MYGA fixed rates and Fixed Indexed Annuity payout factors across 8+ premier Nationwide insurance institutions.
Explain
Transparent debrief on surrender charge years, Market Value Adjustments (MVA), penalty-free 10% liquidity, and income rider costs.
Implement
We coordinate direct trustee-to-trustee rollovers from prior employer 401(k)s or IRAs with zero tax withholding or transfer friction.
Defend
Annual policy reviews to evaluate index crediting performance, track surrender expiration milestones, and coordinate lifetime income activation.
Experience certainty and confidence in your retirement income.
Work directly with Sarah Owens to benchmark guaranteed lifetime payout factors, stress-test surrender schedules, and coordinate direct rollovers. No high-pressure dinner seminars, no opaque sales gimmicks, and zero pressure.
What to have ready for your review
Having these basic details handy helps Sarah model appropriate income scenarios and benchmark top carrier yield tables immediately:
- 1Retirement Timeline & Income Target: Target retirement age, desired monthly guaranteed income, and expected Social Security or pension start dates.
- 2Source of Funds & Tax Classification: Whether funds are Qualified (pre-tax traditional IRA, 401k rollover) or Non-Qualified (after-tax savings, CD proceeds).
- 3Emergency Liquidity Reserves: Verification of liquid emergency cash outside the annuity to ensure you never need to pay premature surrender penalties.
- 4Existing Annuity Statements: Current contract statements showing surrender charge dates, guaranteed minimum rates, and rider values if exploring a 1035 exchange.
Supported Annuity & Retirement insurance carriers
Depending on your age, retirement timeframe, and preference for fixed vs. indexed crediting, Sarah Owens Insurance accesses top-tier top-rated annuity issuers:
 F&G Annuities & Life
 Athene
 Corebridge Financial
 National Life Group
 Americo
 Transamerica
 Mutual of Omaha
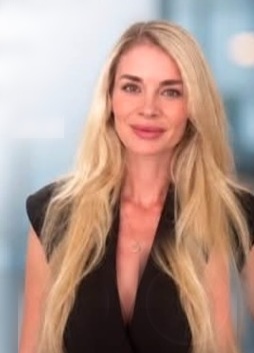
Sarah Owens
Independent Insurance Specialist
Personalized Solutions. Trusted Carriers. Peace of Mind for Your Future.
Choosing the right life insurance, annuity, IUL, supplemental health, or Medicare strategy shouldn't mean navigating a high-pressure call center or settling for a single company's rate sheet.
As an independent, NIPR-verified Insurance Specialist (NPN #22361652), Sarah Owens compares 16+ top-rated insurance and financial companies side-by-side—including F&G Annuities & Life, Foresters Financial, Athene, Transamerica, Mutual of Omaha, National Life Group, Corebridge Financial, Americo, Ethos, Ladder, TruStage, Aflac, Aetna, AIG, and John Hancock Vitality—to design protection around your family's exact goals and budget.
Frequently Asked Questions
Straightforward answers about Fixed Annuities, MYGAs, surrender charges, and lifetime income nationwide.
Is my principal guaranteed against stock market loss in an annuity?
In Fixed and Fixed Indexed Annuities, your principal and credited interest are contractually protected from stock market downturns. If the referenced market index drops 20%, your contract receives a 0% credit for that cycle—never a negative return. However, all guarantees are backed solely by the financial strength and claims-paying ability of the issuing insurer, not the FDIC or federal government. Withdrawals exceeding penalty-free allowances during the surrender period will incur carrier surrender charges and market value adjustments.
Can an annuity guarantee income for the rest of my life?
Yes. Certain annuity contracts and optional Guaranteed Lifetime Withdrawal Benefit (GLWB) riders are specifically engineered to pay a guaranteed income stream for as long as you (or you and your spouse) live, regardless of how long you live or how market indices perform. Sarah helps you benchmark lifetime payout percentages and rider fee structures across top Nationwide carriers.
How does liquidity work, and can I access my funds in an emergency?
Annuities are designed as long-term retirement contracts. Most contracts allow penalty-free withdrawals of up to 10% of contract value each year after the first year. Withdrawals exceeding that allowance during the surrender period (commonly 5 to 10 years) will incur surrender charges and potential Market Value Adjustments (MVA). Sarah ensures you maintain sufficient liquid emergency cash outside of any annuity contract.
How does the IRS tax annuity withdrawals?
Annuities grow tax-deferred. When you take withdrawals, tax treatment depends on how the contract was funded. In Qualified contracts (like a traditional IRA rollover), the entire withdrawal is taxed as ordinary income. In Non-Qualified contracts (funded with after-tax money), earnings are withdrawn first (LIFO) and taxed as ordinary income. Withdrawals before age 59½ may also incur a 10% IRS penalty. Sarah Owens Insurance does not provide tax advice; consult your CPA.
Should I exchange or replace an existing annuity contract?
Replacing an annuity requires extreme caution and a rigorous suitability analysis under State Department of Insurance best-interest standards. Exchanging an existing contract via an IRC § 1035 tax-free exchange may reset surrender charge periods or forfeit valuable legacy guaranteed rates. Sarah conducts an objective line-by-line audit of both contracts before recommending any replacement.
Build a retirement income plan you cannot outlive.
You do not have to sort through complicated annuity surrender schedules and crediting formulas on your own. Tell Sarah your timeline and income goals today. She will help benchmark top Nationwide options and provide transparent recommendations.
All Sarah Owens Insurance annuity products and services are offered exclusively in the United States by Sarah Owens (NPN #22361652, NPN #22361652) under State Department of Insurance best-interest suitability standards. Annuities are long-term insurance contracts issued by life insurance companies and are not bank deposits, not FDIC insured, and not guaranteed by any federal entity. All guarantees, including interest crediting floors and lifetime income streams, are backed solely by the financial strength and claims-paying ability of the issuing insurer. Early withdrawals exceeding contract allowances may incur surrender charges, market value adjustments (MVA), and a 10% IRS penalty if taken before age 59½. This page provides educational information and does not constitute legal, tax, securities, or financial planning advice.